Real estate tokenisation means recording interests in a property as tokens on a blockchain. In the UK a token almost never represents the land itself. HM Land Registry records the legal owner, usually a company formed for the property, and the tokens record shares in that company. The structure, not the token, decides what a holder owns.
What does a property token give its holder?
A property token gives its holder whatever the legal structure behind it gives, which in the UK is usually a share in the company that owns the property, or a debt that company owes. Neither is a direct interest in the bricks.
Three records sit in a chain, and each decides a different question. HM Land Registry's register of title decides who owns the land: a person entered as proprietor of a legal estate is treated as holding it (Land Registration Act 2002, s58), and a transfer of registered land does not take effect at law until it is registered (s27). In a tokenised property that proprietor is the company. The company's register of members decides who owns the company: every company must keep one (Companies Act 2006, s113), and it is prima facie evidence of what it records (s127). The blockchain records which wallet holds how many tokens.
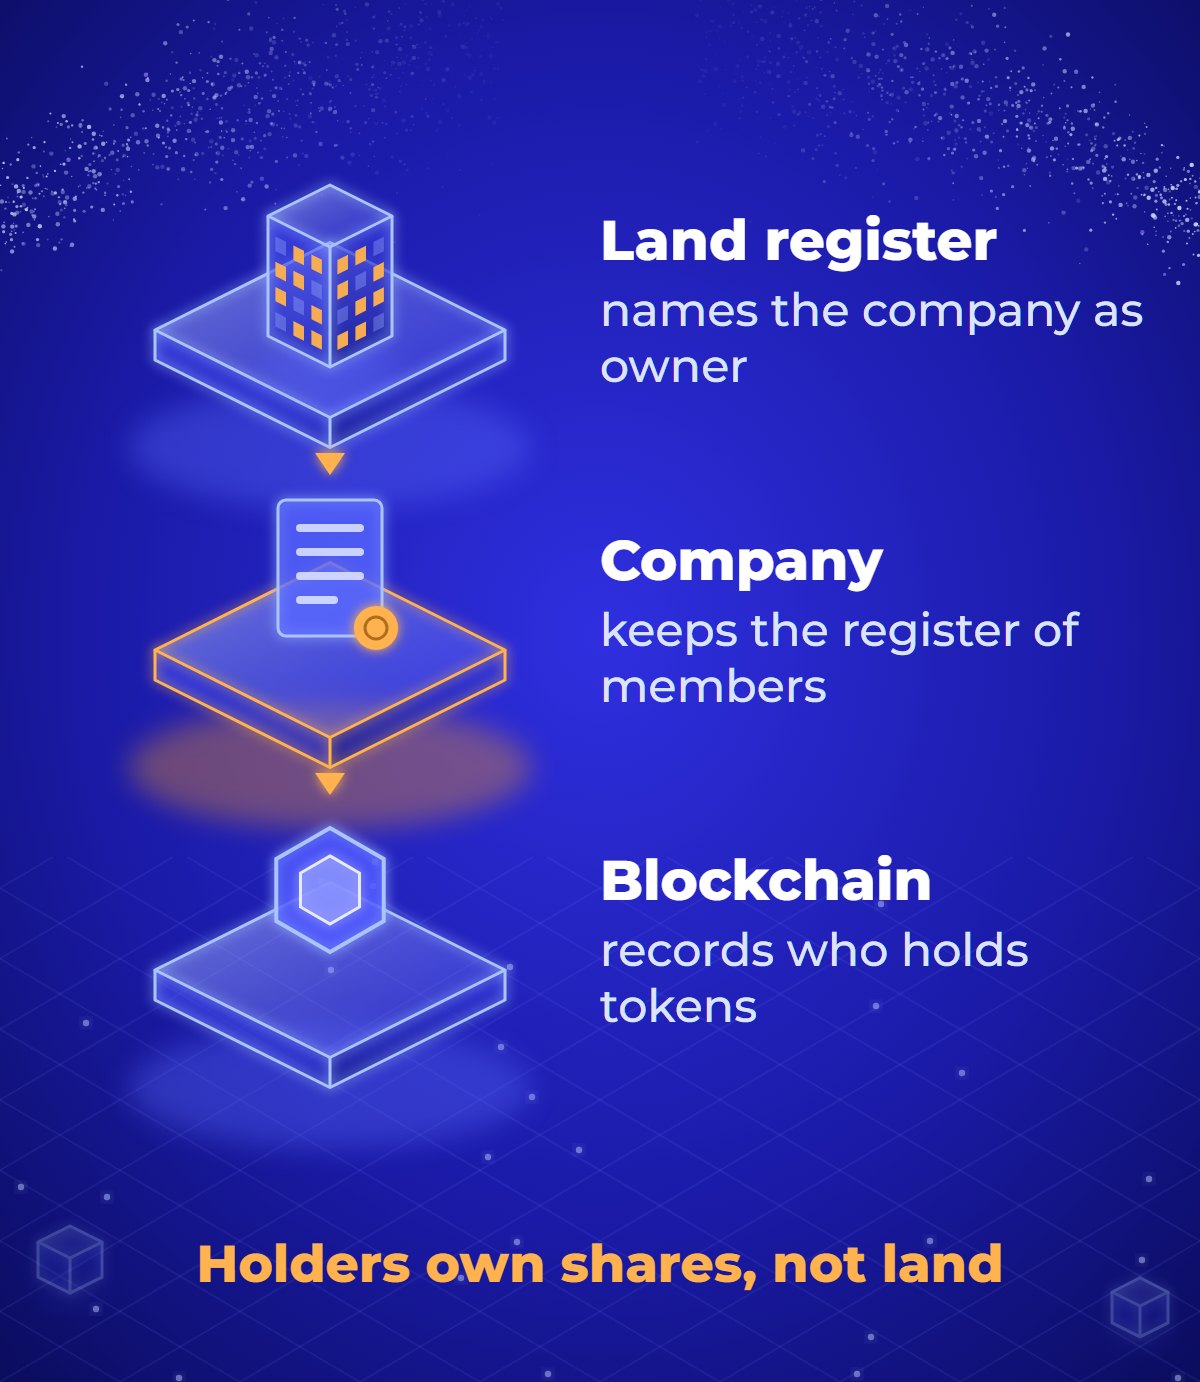
The land register names the company. The tokens follow the company's share register, not the title.
Moving a token does not, by itself, change the register of members. A company may register a transfer of its shares only when a proper instrument of transfer has been delivered to it or an exemption applies (Companies Act 2006, s770, all sections checked 3 October 2026). The articles of association and holder terms must say how an on-chain transfer becomes one the company can register, and who updates the register. Where they are silent, the blockchain and the register drift apart, and the register is the record a court starts from.
What a holder can enforce follows from the instrument: a shareholder has the rights company law and the articles give, a lender the rights in the loan agreement. As What is asset tokenisation? explains for every asset class, the token records a right and the structure creates it.
Why the land itself is not split into tokens
In England and Wales, land cannot be held at law by hundreds of token holders, because the law allows no more than four legal owners.
Two 1925 statutes set the limit. Where land is conveyed to more than four people in undivided shares, the conveyance operates as a transfer to the first four named, who hold it on trust for everyone interested (Law of Property Act 1925, s34). Trustees of land may not exceed four (Trustee Act 1925, s34, both checked 3 October 2026). Everyone else holds a beneficial interest behind a trust.
A scheme that offers "fractions of a house" directly therefore ends up as a trust: up to four trustees on the title, and a list of beneficiaries kept off the register. A trust in which many people share the rent while a manager runs the building is also the shape the collective investment scheme rules were written for, as the section on which UK rules apply explains.
A company solves both problems: one registered proprietor that does not change when holders change, and a register built for many members. That is why UK property tokenisations usually hold the land in a company formed for the purpose, a special purpose vehicle (SPV). These statutes extend to England and Wales; Scotland has its own land law, so where the property sits is the first question for a property lawyer.
Which UK rules apply to a property token?
Tokenised property is lawful in the UK, and two bodies of law decide how it is treated: property law for the token itself, and financial services law for what the token represents.
On the first, the Property (Digital Assets etc) Act 2025, in force since 2 December 2025 in England and Wales and Northern Ireland, confirms that a digital thing can be the object of personal property rights. That helps when a token is stolen, inherited or caught in an insolvency. It does not change what the token represents.
On the second, the decisive question is whether the arrangement is a collective investment scheme. The Financial Services and Markets Act 2000 defines one as arrangements that let participants share in profits or income from property they do not control day to day, where contributions are pooled or the property is managed as a whole (FSMA 2000, s235). A fractional property scheme in which an operator manages a building and shares out the rent meets each part of that description unless an exclusion applies.
The consequences are heavy. Operating a collective investment scheme is a regulated activity (Regulated Activities Order 2001, art 51ZE) needing authorisation from the Financial Conduct Authority (FCA), and an authorised person may not promote an unauthorised scheme to the public unless an exemption applies (FSMA 2000, s238).
A company sits on the other side of that line. The Collective Investment Schemes Order provides that no body corporate other than an open-ended investment company is a collective investment scheme, and it expressly withholds that exclusion from limited liability partnerships (SI 2001/1062, Schedule, paragraph 21). This is one reason a limited company, rather than an LLP or a trust, is the usual holding vehicle.
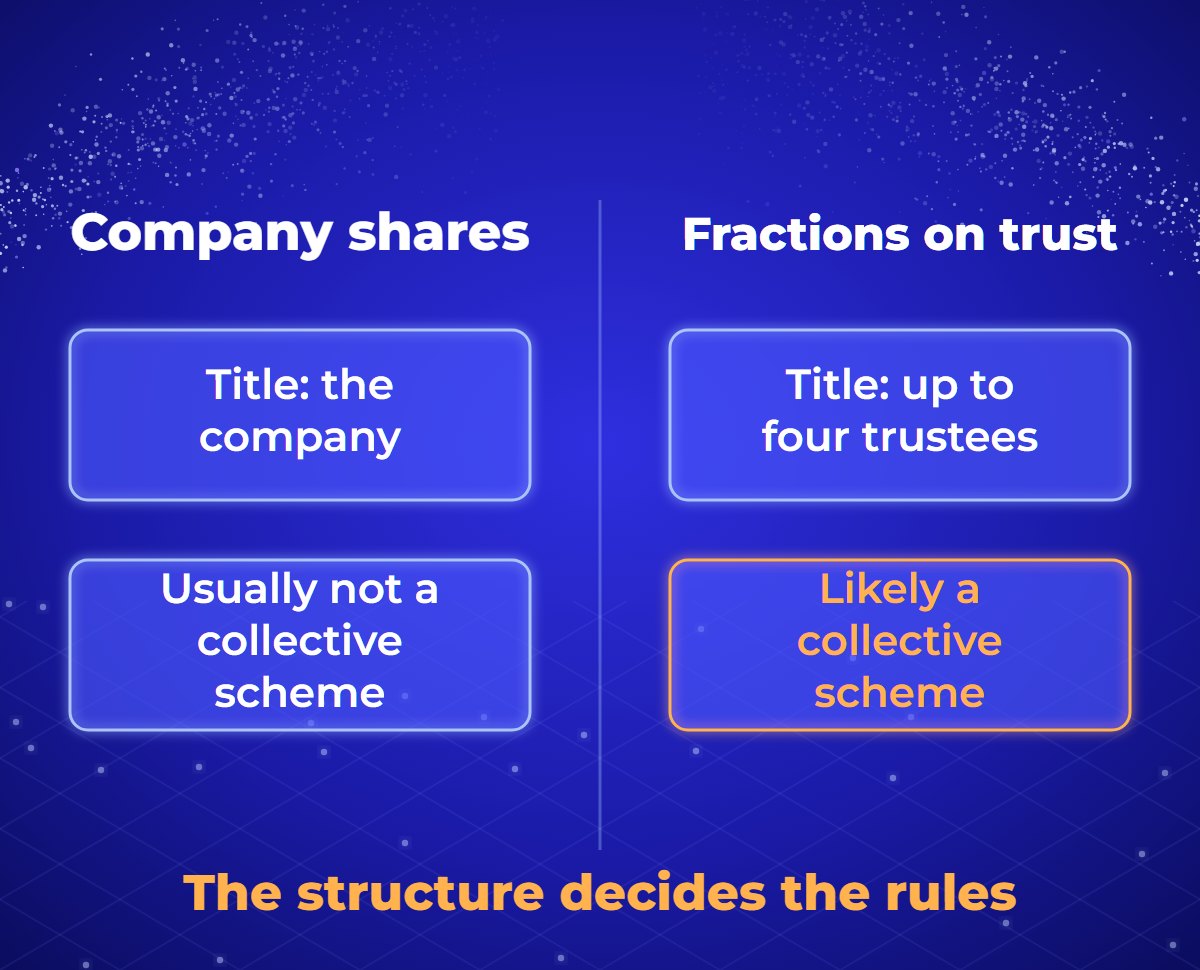
The holding vehicle decides which regulatory regime the project starts in.
A company does not escape financial regulation altogether. Its shares and debt securities are investments, and a business that invites people to acquire them must be an authorised person or have the invitation approved by one, unless an exemption applies (FSMA 2000, s21). A company that raises money from many people to deploy under a defined policy can also be an alternative investment fund, which may be constituted "in any legal form" (Alternative Investment Fund Managers Regulations 2013, reg 3; legislation checked 3 October 2026). Whether either applies is a question for a regulatory lawyer, answered before the token is designed.
The FCA's April 2026 guidance on tokenised funds likewise works "within the regulator's existing rules" (FCA, PS26/7, 30 April 2026): a blockchain record does not change the regulatory treatment.
How a property tokenisation is structured
A UK property tokenisation runs in seven steps, and only one of them, issuing the token, is blockchain work.
Confirm title and the lender's position. Who owns the property, what is registered against it, and whether a lender must consent.
Form the holding company and move the property into it. Stamp Duty Land Tax on a transfer to a connected company is charged on at least market value, even when no cash changes hands (Finance Act 2003, s53). Residential property costing more than £500,000 bought by a company is charged at 17% unless a relief applies, such as use in a property rental business (HMRC, SDLT: corporate bodies). A company holding a dwelling valued above £500,000 may also owe the Annual Tax on Enveloped Dwellings each year (HMRC, ATED; all checked 3 October 2026). SDLT applies in England and Northern Ireland; Scotland and Wales have their own land taxes.
Choose the instrument. Ordinary shares, redeemable shares, a bond or a participating loan. The choice drives the regulatory and tax analysis.
Decide who may hold it. Countries, holder categories, identity checks, and whether onward transfer is allowed. Keep the verification data off the blockchain; a public ledger exposes every holder permanently.
Prepare the documents. The offering document, articles that tie token transfers to the register of members, and any financial promotion approval.
Issue the token. Supply, divisibility, and which control addresses are set and who holds them.
Operate. Collect rent, pay distributions, reconcile the register with the ledger, file accounts and report to holders.
Trusty Digital's 2023 residential pilot, a complex of 300 private houses held through a project structure, followed this order. The participation model was defined in documentation; the token profile, transfer rules and participant onboarding were configured to match it; ownership and transfers were recorded on Algorand. In such projects Trusty Digital configures the rules and runs the operational layer; legal work is done by the client's advisers. The pilot is summarised, without client names, in the use cases by industry.
Is tokenised property liquid?
No. A token moves in seconds, but transferability is not liquidity, and this is the claim most property tokenisation pages get wrong.
Liquidity means a willing buyer, at a price close to the last one, when you want to sell. A tokenised property interest is a share in a private company holding one illiquid asset, often restricted to certain holders, with no venue on which it trades. Even where a venue exists, a single-property company is a thin market.
The market is also small. On 3 October 2026, RWA.xyz counted $226.7m of tokenised real estate that holders can move between wallets, about 0.6% of the $38.68bn of such tokenised assets it tracks, excluding stablecoins.
A transfer also carries steps the blockchain does not remove. The buyer must pass the eligibility rules, the company must register the transfer, and the tax has to be accounted for: buying existing shares in a UK company usually carries a 0.5% tax, as Stamp Duty or, for electronic transfers, Stamp Duty Reserve Tax (HMRC, Tax when you buy shares, checked 3 October 2026). How it applies to token transfers is a question for a tax adviser.
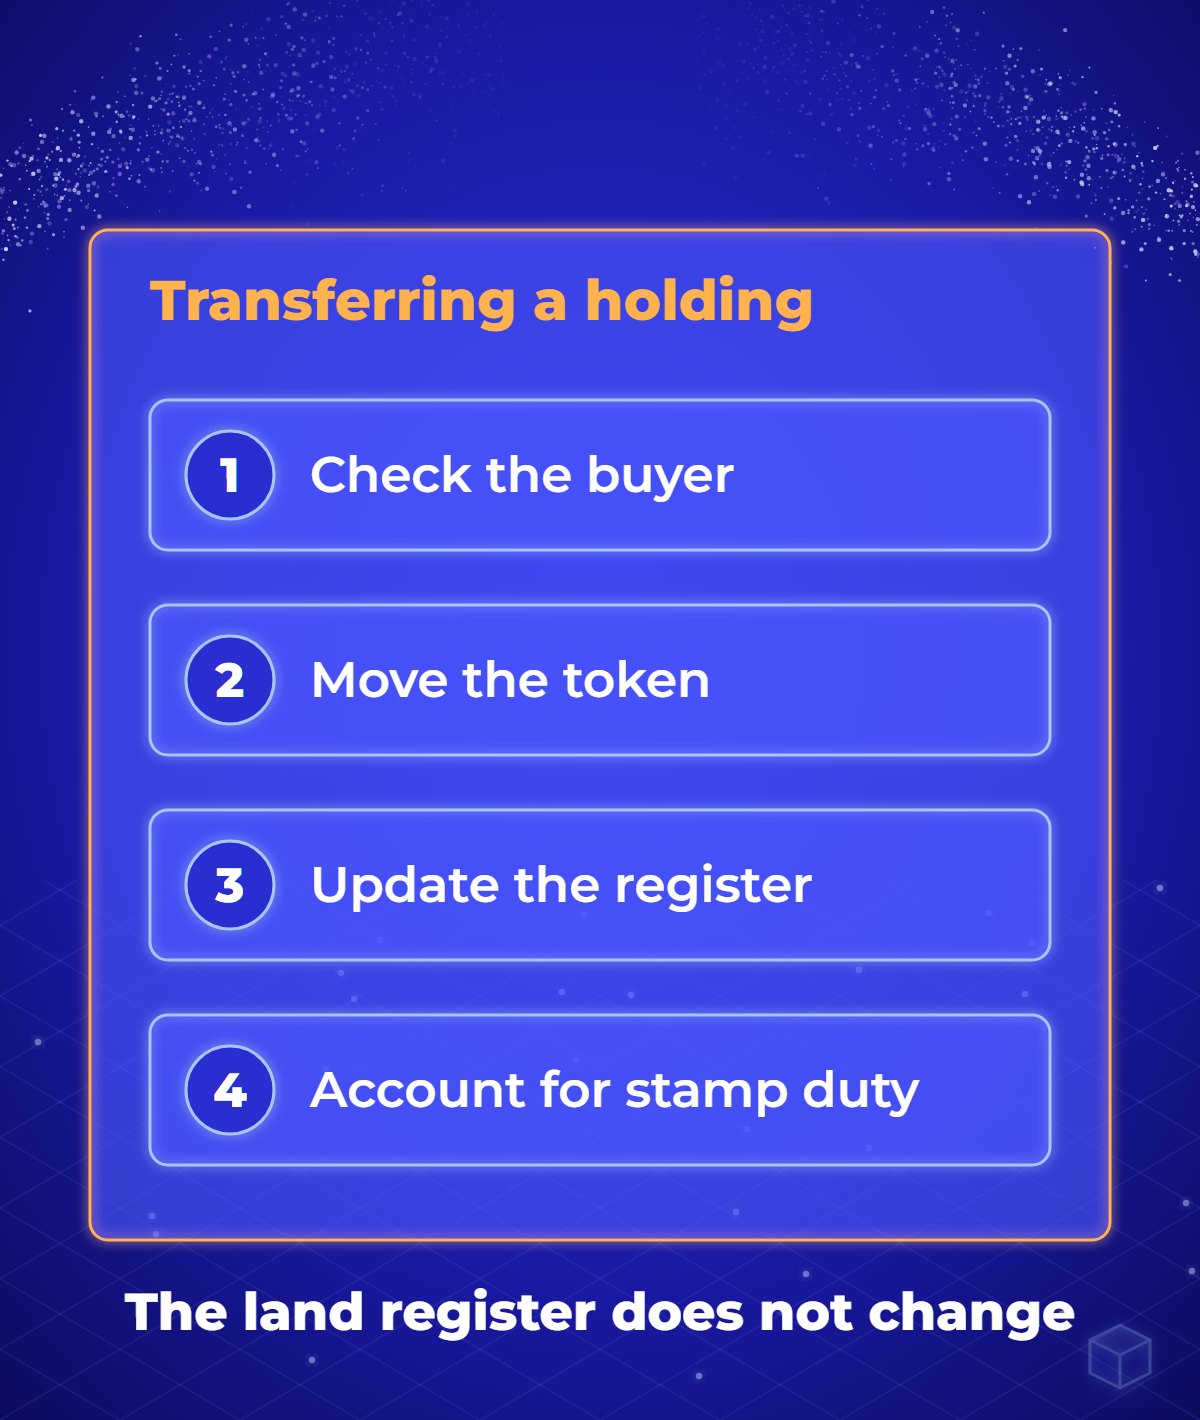
The token moves in seconds. The register, the checks and the tax still have to follow.
Where a structure improves the prospect of a transfer, say precisely how: a named venue, a matching facility, a buy-back undertaking with a stated source of funds. Atomic transfers can settle both sides at once, but only when the payment is on the blockchain too. Trusty Digital does not describe tokenised property as liquid.
Where property tokenisations fail
Most property tokenisations that fail do so on lender consent, tax, promotion or cost, each checkable in the first weeks.
Lender consent. An existing mortgage commonly restricts transferring the property or changing who owns the borrowing company. Found late, it stops the project.
Tax on the move into the company. Market-value SDLT, the 17% rate where it applies and the annual enveloped dwellings charge can make the exercise uneconomic. Asked in week one, it is a modelling task; in month four, a write-off.
A promotion nobody approved. A website that invites the public to acquire shares in the property company is a financial promotion. Without an authorised person behind it, or an exemption, it breaches section 21.
Valuation. The value has to come from a qualified valuer independent of the issuer. A figure produced by the issuer is not a valuation.
Operating cost. Distributions, reporting, register maintenance and accounts scale with the number of holders: two hundred small holders cost more to serve than three large ones. Model it before issuing.
Control nobody disclosed. A token can carry addresses that freeze a holding or move it without the holder's consent. A property company has legitimate uses for them: a court order, a failed verification, a register correction. On Algorand these settings are public, so disclose whether they are set, who controls them and when they would be used, before a holder finds them on a block explorer.
Is your property suitable?
A property suits tokenisation when its title is clean, its income is predictable, its value makes division useful, its holders can be identified, and its administration is costly relative to the asset. It does not suit when the title is contested, the lender will not consent, the value rests on one tenant or one planning decision, or nobody can say who would acquire the units.
Questions people also ask
Will token holders appear on the Land Registry title? No. The registered proprietor is the company, whoever holds the tokens. Holders appear in the company's register of members, which has to be kept in step with the blockchain.
Can a mortgaged property be tokenised? Only with the lender's agreement where the mortgage terms require it, and they usually restrict both a transfer of the property and a change in who owns the borrower. Ask before any structure is built.
Is a fractional property platform a collective investment scheme? Often, if holders share the income from a building that someone else manages and the arrangement is not held in a company. Section 235 of FSMA 2000 sets the test and the Collective Investment Schemes Order lists the exclusions; a regulatory lawyer applies them to the actual documents.
The short version
A UK property token is almost always a share in, or a loan to, the company that owns the building, and the land register and the register of members, not the blockchain, decide who owns what. A company keeps the title stable and is excluded from the collective investment scheme definition, but financial promotion rules still apply to its shares. Tokenisation makes the register cheaper to run and easier to check; it does not make the property liquid. Lender consent, tax and the link between token and register decide most projects, and all three can be settled before any token exists.
For a first view of your own property, the free Tokenisation Fit Check takes a few minutes. It is based only on your answers and is not advice, but it shows which of these questions are still open for your project.
This article is general information, not legal, tax or investment advice.


 10 min read