Asset tokenisation means recording rights in an asset (property, equipment, a share in a company, a revenue stream) as digital tokens on a blockchain. The token is a record of a right, not the right itself. The right is created by the legal structure behind it, which has to be built whether or not a blockchain is involved.
What a token actually is
A token is an entry on a shared ledger that says a particular account holds a particular quantity of a particular asset. That is the whole of it. The ledger is kept by a network of computers rather than by one institution, so anyone can check the entry and nobody can quietly edit it afterwards.
What the token does not do is create the right it refers to. If a token represents a share in a company, the share exists because company law and the company's articles say it does. If it represents a claim on rental income, the claim exists because a contract creates it. Issuing the token records that position on a ledger; it does not bring it into being.
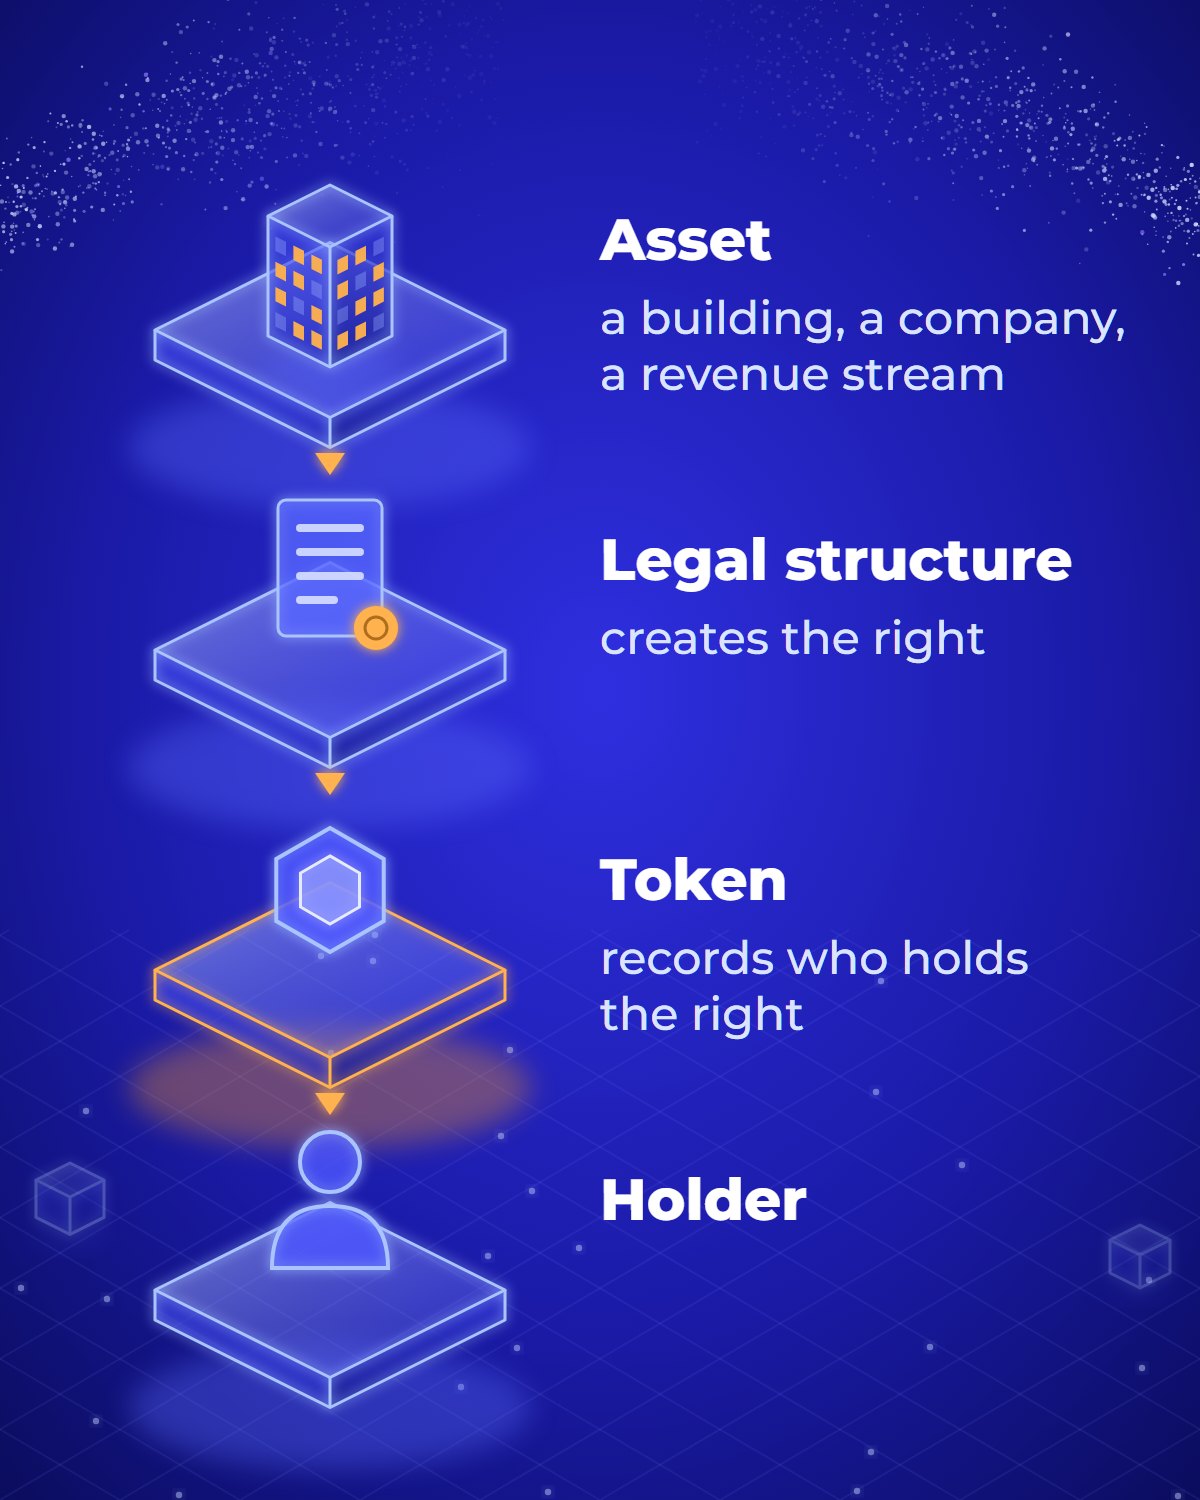
The legal structure creates the right. The token records who holds it.
This is the distinction most explanations skip, and it is the one that matters most in practice. A tokenisation project is a legal structuring exercise with a technical implementation attached, not a technical project with some paperwork at the end. Budget, timeline and risk all follow from which way round you have it.
Why put the record on a blockchain at all? Three properties do useful work.
The record settles quickly and stays settled. On Algorand, the blockchain Trusty Digital uses, a block is confirmed every 2.82 seconds on average, and once it is certified its transactions "are final and cannot be reversed" (Algorand Developer Portal, checked 3 October 2026).
The record can be inspected. Anyone can see how many tokens exist, who holds them and when they moved, without asking the issuer.
A transfer is cheap. The standard fee is 0.001 ALGO while the network is not congested (Algorand Developer Portal, checked 3 October 2026), a small fraction of a penny, so moving a small unit does not cost more than the unit is worth.
Together these make it practical to divide an asset into many units and keep an accurate register of who holds them, without an administrator reconciling spreadsheets.
How big is the tokenised asset market?
Smaller than most headlines suggest. On 3 October 2026, RWA.xyz, which tracks real-world assets on public blockchains, counted $38.7bn of tokenised assets that holders can move freely between wallets, not counting stablecoins.
The figures below all come from RWA.xyz on that same day, so they can be compared with each other:
- $38.68bn of "distributed" assets: tokens that can leave the issuing platform and pass from one wallet to another.
- $388.75bn of "represented" assets: assets recorded on a shared ledger that cannot be moved between wallets.
- $294.89bn of stablecoins, which RWA.xyz counts separately.
- $14.77bn in tokenised US Treasury funds, about 38% of the distributed total.
- $226.7m in distributed tokenised real estate, about 0.6% of it.
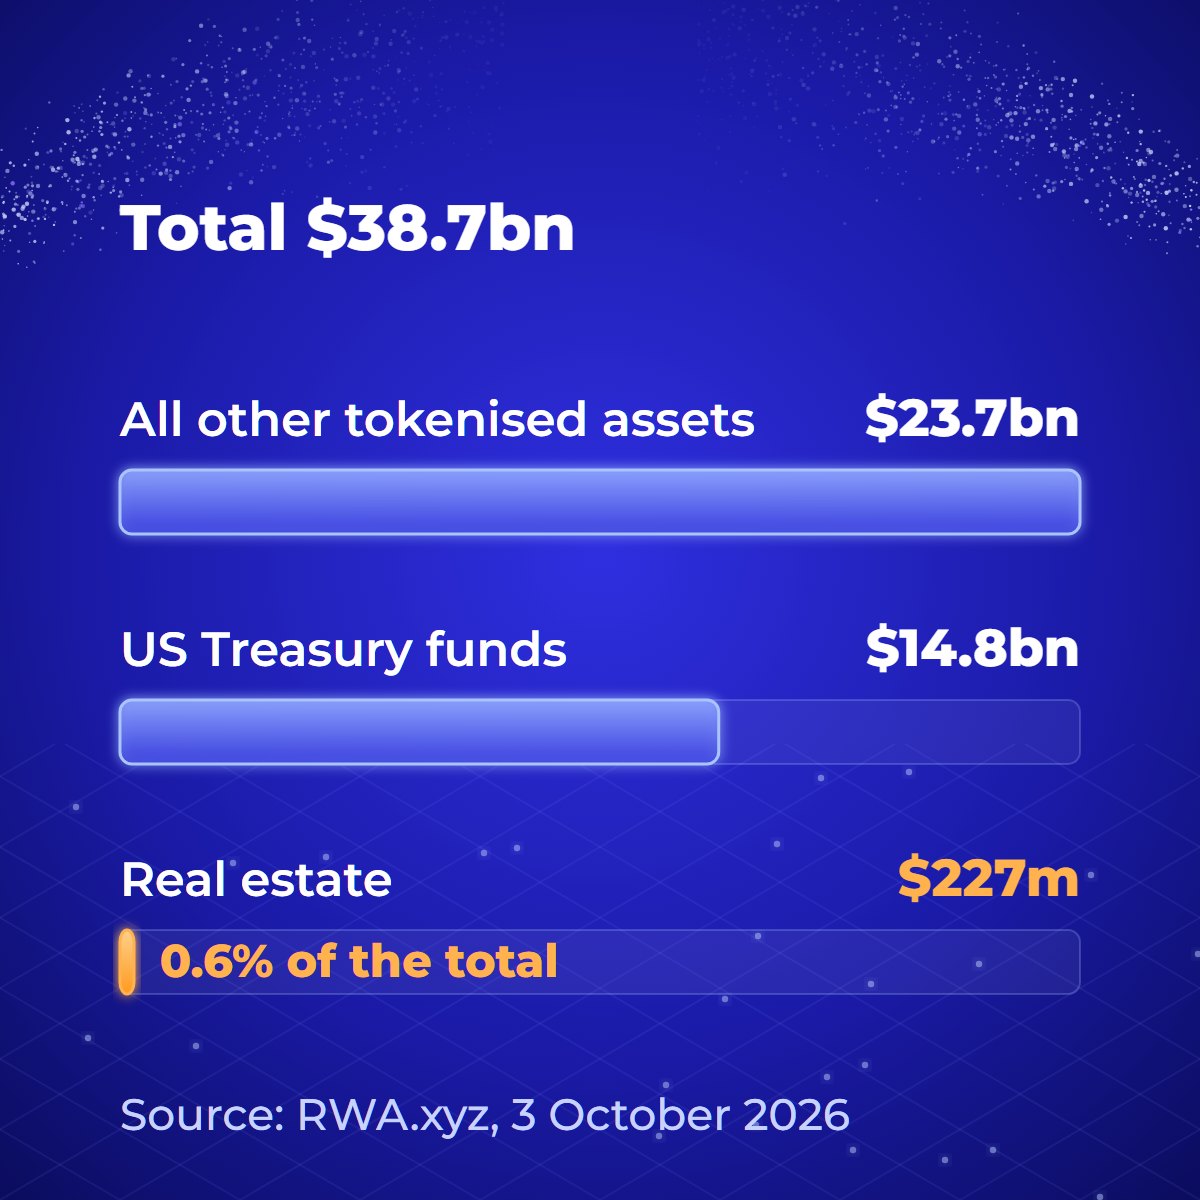
Tokenised assets that holders can move between wallets, excluding stablecoins, on 3 October 2026. Source: RWA.xyz.
This is why market-size claims disagree. The same tracker publishes two totals ten times apart, and adding stablecoins multiplies the figure again. Before relying on any number, ask which of the three it counts: transferable tokens, assets only recorded on a ledger, or stablecoins. A source that does not say is not a source. RWA.xyz explains its two categories in its note on distributed and represented assets.
The composition matters more than the total. Most tokenised value sits in government debt and money-market funds: assets that were already liquid, already standardised and already traded electronically. Property, private credit and equipment make up a far smaller and much harder segment. That is where the structuring work is real, and it is the segment most readers of this article are in.
What actually happens in a tokenisation project
The technical step is the short one. In rough order:
Establish what is being tokenised and who owns it. Clear title, a clean chain of ownership, and an asset that can lawfully be divided or transferred at all. A surprising number of projects stop here.
Decide what the token represents. A share in a company that owns the asset, a debt instrument, a contractual right to revenue, or a membership right. Each has different consequences in company law, tax and financial regulation, and the choice is made with legal advisers rather than with a developer.
Build the holding structure. Often a company or a special purpose vehicle (SPV) holds the asset and issues the instrument. The structure, not the blockchain, is what gives a holder a claim.
Settle the rules for holders. Who may hold the instrument, in which countries, after what checks, and whether it can be passed on. Decide this before issuance, because it shapes how the token is set up.
Prepare the offering and the disclosures. What prospective holders are told, in which document, approved by whom.
Issue the token. How many units, what each one records, and who keeps which powers over it, such as the power to freeze a holding.
Operate it. A register that stays accurate, reports to holders, distributions, and a process for transfers and corrections.
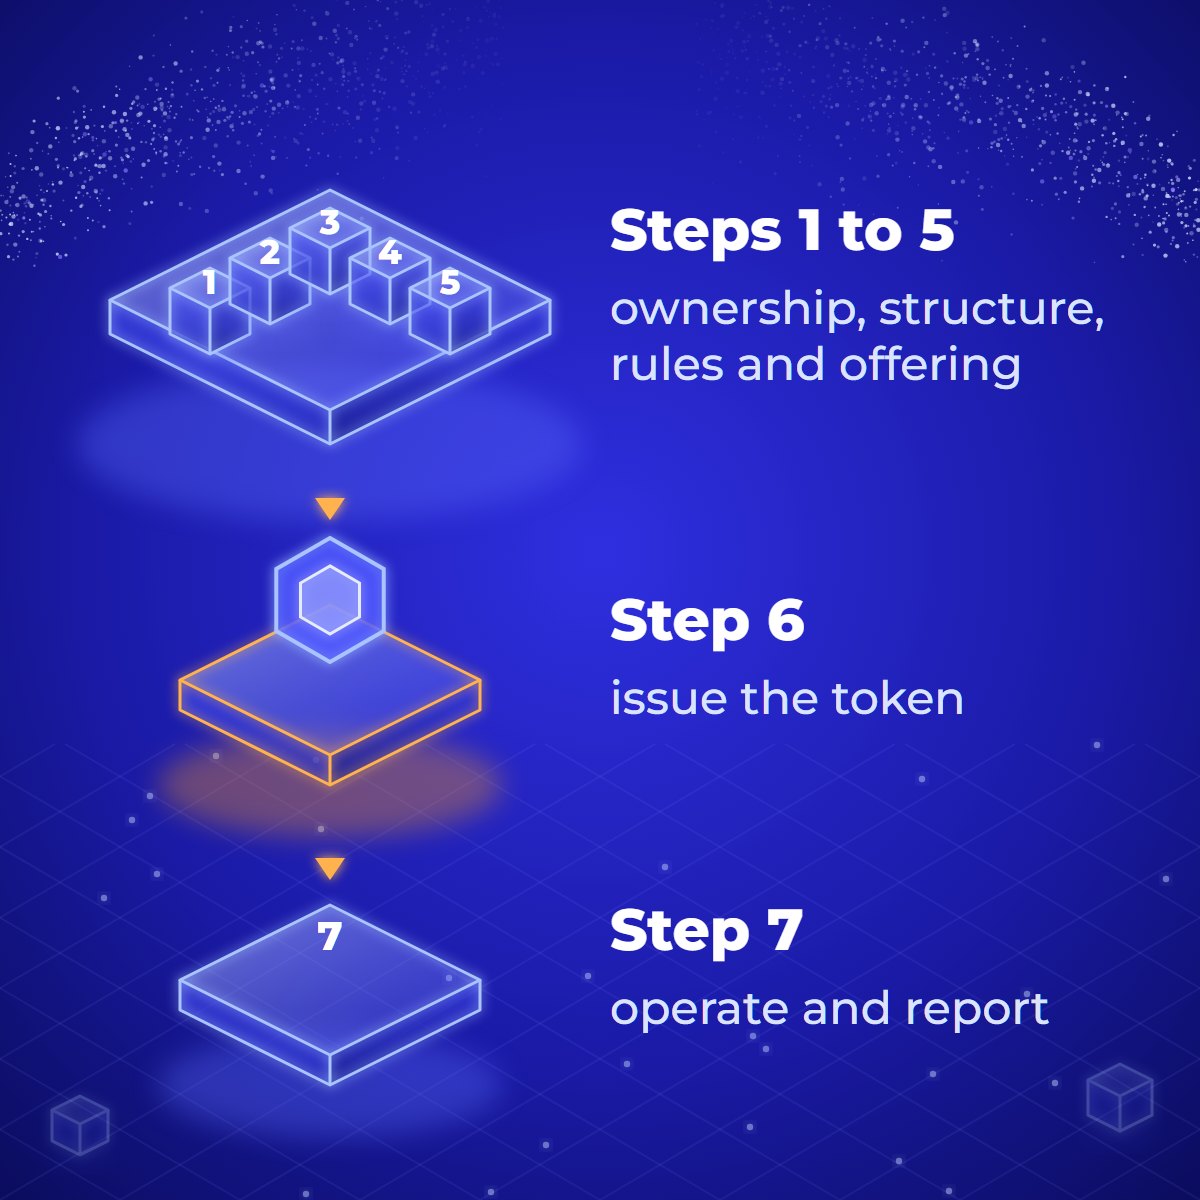
Five of the seven steps happen before any token exists.
The first five steps are legal, commercial and operational. Only the sixth involves a blockchain, and it is usually the fastest part of the programme. If a supplier's proposal is mostly about that step, it is a proposal for the easy part.
Is asset tokenisation legal in the UK?
Yes. Nothing in UK law stops an asset from being recorded as tokens, and the law of England and Wales now says expressly that a digital asset can be property. What the token represents still decides which rules apply to it.
The Property (Digital Assets etc) Act 2025 received Royal Assent on 2 December 2025 and took effect the same day. It confirms that a thing, including a digital one, can be the object of personal property rights even though it is neither a physical object nor a right that exists only to be claimed through the courts, the two categories English law traditionally recognised. That gives holders, courts and insolvency practitioners firmer ground when a token is stolen, inherited or caught up in a failure. The Act extends to England and Wales and to Northern Ireland, not to Scotland.
Recognising a token as property does not change what it represents. If it represents a share, a bond or a unit in a fund, it is a financial instrument, and the rules on offering it, promoting it and dealing in it apply exactly as they would on paper. The Financial Conduct Authority made the same point for authorised funds in April 2026, when it set out how fund managers can use blockchain records "within the regulator's existing rules" (FCA, policy statement PS26/7, 30 April 2026). In May 2026 the FCA and the Bank of England asked the market for views on how tokenisation should develop in UK wholesale markets (Bank of England, 18 May 2026).
The European Union draws the same line. Its crypto-asset regulation, MiCA, states that it does not apply to crypto-assets that qualify as financial instruments (Regulation (EU) 2023/1114, Article 2(4)); those stay under the EU's existing securities rules. A token that is not a financial instrument, such as one that gives access to a service, may fall under MiCA instead.
So the first legal question in any project is what the token represents, and it is a question for a solicitor, not a developer.
What tokenisation does not change
It does not create a market. A token can be transferred easily; that is a technical property. Whether anyone wants to buy it is a commercial question, and dividing an asset into units does not produce anyone willing to acquire them.
It does not change the regulatory position. An instrument that is regulated when recorded in a register is regulated when recorded on a blockchain. The form of the record is not what determines the treatment.
It does not verify the asset. A ledger records that a token exists and who holds it. It says nothing about whether the property is worth what the issuer claims, whether the title is sound, or whether the business will perform.
It does not remove the need for administration. Registers still need maintaining, holders still need reporting to, distributions still need paying. Some of this becomes easier. None of it disappears, and a vehicle with two hundred small holders costs more to run than one with three large ones.
It does not make a transfer reversible. The finality that makes settlement useful also means an error stands. A transfer to a wrong address is not undone by asking.
What can go wrong
Tokenising something that cannot lawfully be divided. Discovered late, after the technical work is done.
Treating the token as the instrument. If the legal structure is thin, holders own a ledger entry pointing at nothing enforceable.
Keeping control nobody disclosed. A token can be issued with powers that let the issuer freeze a holding or move it back without the holder's consent, often called freeze and clawback. That is sometimes appropriate, for example as the way an issuer gives effect to a court order or a transfer restriction, but it has to be deliberate and disclosed. Holding a token does not always mean controlling it, and the settings are published on the ledger for anyone who thinks to look.
Publishing information that cannot be withdrawn. Anything written into a transaction note, or published to a permanent file network such as IPFS, stays public for good. Personal data should never go near either.
Assuming a project will raise money because it is tokenised. It will not. The structure changes how ownership is recorded and transferred. It does not create demand.
Is tokenisation right for your asset?
It tends to suit assets that are genuinely divisible, that produce something measurable, that have a clean ownership position, and where the current administration is costly relative to the value being administered. Tokenising property is the most common case and shows the pattern clearly, and the use cases by industry show how the same method applies to energy, commodities, art and credentials.
It tends not to suit assets whose ownership is contested, that cannot be divided without breaking something, or where the actual problem is that nobody wants to buy them. Tokenisation does not solve the last one, and it is the most common reason a programme should not start.
Questions people also ask
Is a tokenised asset the same as a cryptocurrency? No. A cryptocurrency such as bitcoin is the asset itself, with nothing standing behind it. A tokenised asset is a record of a right in something that exists off the blockchain, such as a building, a company or a contract, and what it is worth depends on that right being enforceable.
Can any asset be tokenised? Technically, almost anything can be recorded as a token. In practice it only makes sense for an asset whose ownership is clear and which can lawfully be divided or transferred, and many assets fail that test.
Does tokenisation make an asset easier to sell? It makes a transfer easier to carry out, not a buyer easier to find. Whether anyone wants the units is a commercial question that the token does not answer.
The short version
A token records a right; the legal structure creates it. Most of a tokenisation project is therefore legal and commercial work, and the blockchain step is the quick part. Tokenisation makes a register cheaper to run and easier to check, and English law now treats digital assets as property, but it does not create buyers, change the regulatory position or vouch for the asset. If your asset is divisible, cleanly owned and costly to administer, it is worth a closer look.
For a first view of your own asset, the free Tokenisation Fit Check takes a few minutes and needs no account. It is based only on your answers and is not advice, but it shows which questions your project has not yet answered.
This article is general information, not legal, tax or investment advice.


 10 min read